Expense rules catch small business owners out in both directions: some people under-claim out of caution, missing out on legitimate deductions, while others over-claim by accident and risk an awkward conversation with HMRC later. Here’s a practical guide to what generally counts, and where the genuine grey areas are.
The general rule
HMRC’s test is that an expense must be “wholly and exclusively” for the purposes of the business. In practice, that means: if you wouldn’t have spent the money if you didn’t run the business, it’s probably allowable. If you’d have spent it anyway regardless of the business, it probably isn’t. Most of the genuinely difficult cases sit somewhere in between, which is where judgement (and a fair, defensible method) matters more than a simple yes/no rule.
Common allowable expenses
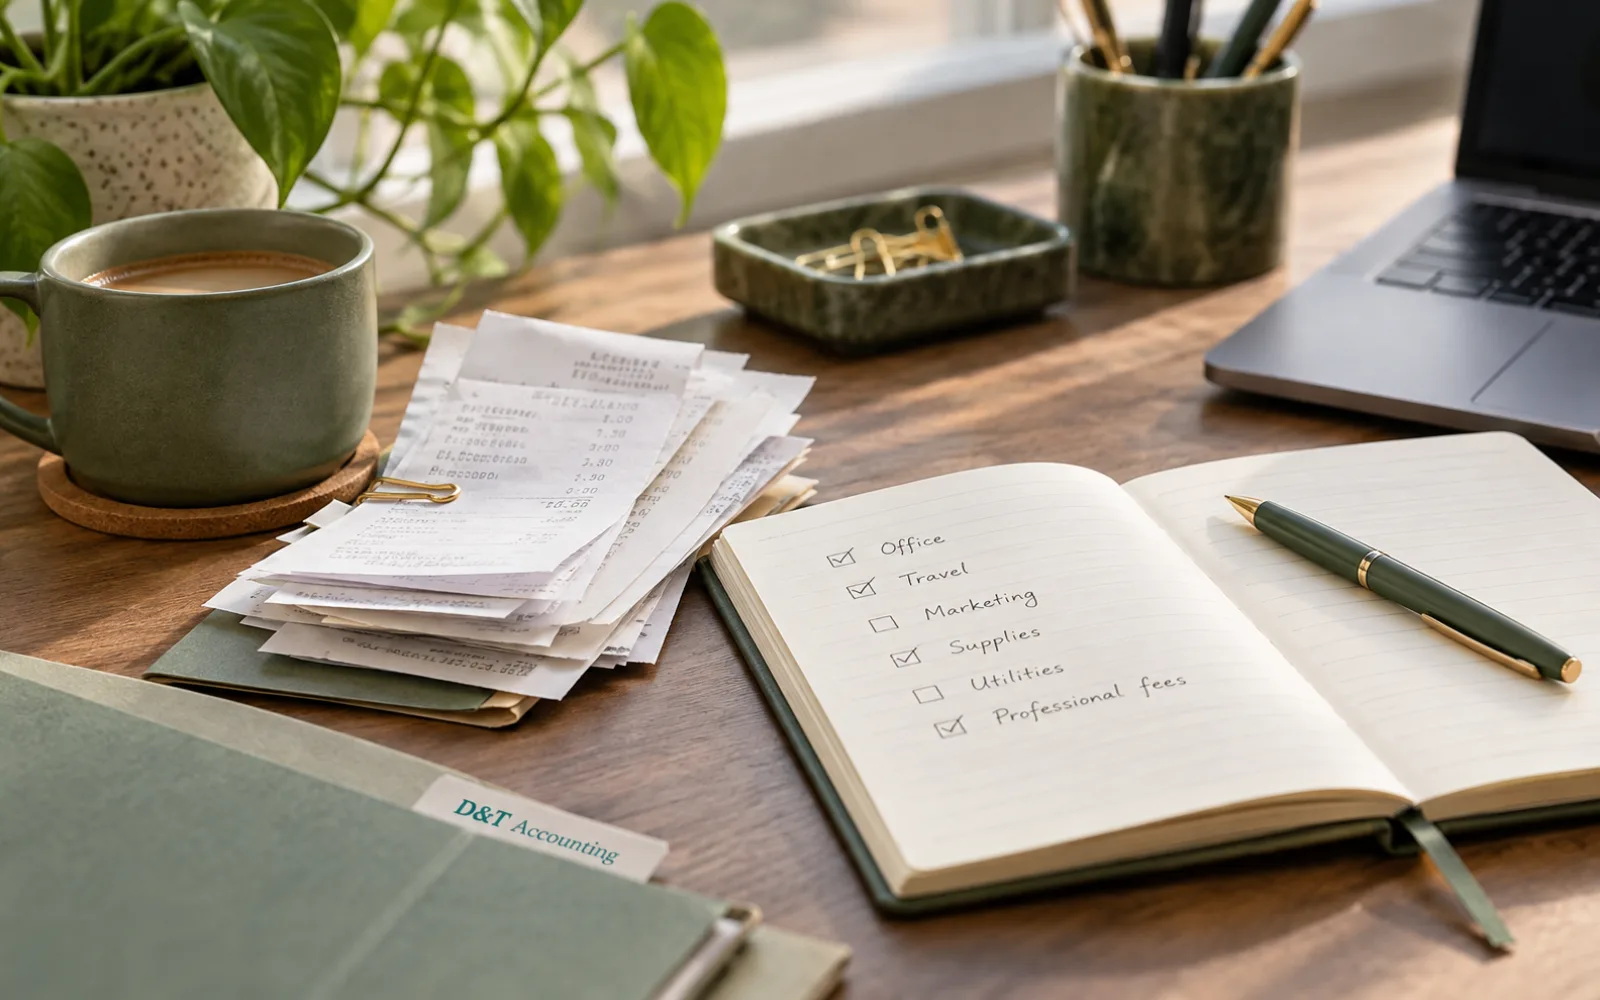
- Office costs – stationery, software subscriptions, business phone and internet
- Travel for business purposes – fuel, parking, train fares (not your regular commute, if you have a fixed base)
- Marketing and advertising – website costs, printed materials, paid ads
- Professional fees – accountancy, legal advice, business insurance
- Equipment and tools needed to do the work
- A proportion of home costs if you work from home, calculated fairly rather than guessed
Where it gets genuinely grey
Clothing is a common source of confusion: a branded uniform or protective workwear is allowable, but a suit you could also wear outside work generally isn’t, even if you only actually wear it for client meetings. Entertaining clients is another – the cost of taking a client to dinner typically isn’t an allowable expense for tax purposes, even though it’s a completely normal, legitimate business activity. These rules can feel counterintuitive, which is exactly why they trip people up.
Capital expenses are treated differently to day-to-day costs
Buying a laptop, van, or piece of equipment that will last several years isn’t treated the same way as buying stationery or paying a software subscription – these are capital items, and relief for them usually works through capital allowances rather than being deducted as a simple expense in the year you bought them. The practical effect for many small businesses is similar (most of the cost is still relieved against tax), but the mechanism and timing differ, and it’s worth knowing the distinction exists rather than assuming every purchase is treated identically.
Training and professional development: it depends what the training is for
Training that maintains or updates your existing skills and knowledge in your current trade is generally allowable. Training that gives you a wholly new skill or qualification – moving into a different field entirely – is treated differently, and often isn’t. The line between “updating what I already do” and “becoming qualified to do something new” isn’t always obvious, so if you’re investing in a significant course or qualification, it’s worth checking before assuming it’s a straightforward deduction.
Mixed-use costs need a fair, defensible split
Your phone bill, your car, your home office – if something is used for both business and personal purposes, you can only claim the business proportion, and that proportion needs to be calculated on a reasonable basis (mileage logs, hours worked from home, percentage of calls) rather than picked as a round number that happens to feel fair. HMRC doesn’t expect perfection here, but it does expect a method you could explain and defend if asked.
Keep the evidence, not just the number
A claimed expense without a receipt or record behind it is a liability if HMRC ever asks. This is less about rules and more about habit – the business owners who find expense claims stressful are almost always the ones trying to reconstruct records after the fact, rather than keeping them as they go. See our Bookkeeping page for how we help with exactly this.
Expenses people often wrongly assume aren’t claimable
It’s not all caution and grey areas – there are legitimate expenses people frequently miss because they assume, incorrectly, that they don’t count. Reasonable subsistence costs while travelling for business (a meal while away overnight, for example, as distinct from entertaining a client) are generally allowable. Subscriptions to professional or trade bodies relevant to your work usually are too. Bank charges and interest on business borrowing are often allowable in full. If you’ve been assuming something is a personal cost out of caution rather than certainty, it’s worth checking rather than quietly missing out on a legitimate claim year after year.
When in doubt, ask before you claim
The cost of asking whether something is allowable is far lower than the cost of an incorrect claim being queried later. This is normal, routine work for an accountant – not something to feel embarrassed about checking, and not a sign you’re doing something wrong by asking.
Not sure what you can claim?
We review this as part of preparing every Self Assessment return – get in touch and we’ll go through your specific situation.